


 Deutsch
 English
 Español
 Français
 Nederlands
 Português


 Share





In early 2026, AI chip export controls are redrawing the global semiconductor map at a pace not seen since the Cold War. The U.S. has activated $52 billion in CHIPS Act grants, catalyzing $450 billion in private investment, lifting its advanced chip capacity share from 12% to roughly 22%. Beijing is racing to build domestic alternatives, fragmenting supply chains and adding 25–35% to landed costs.
The New Silicon Curtain: How We Got Here
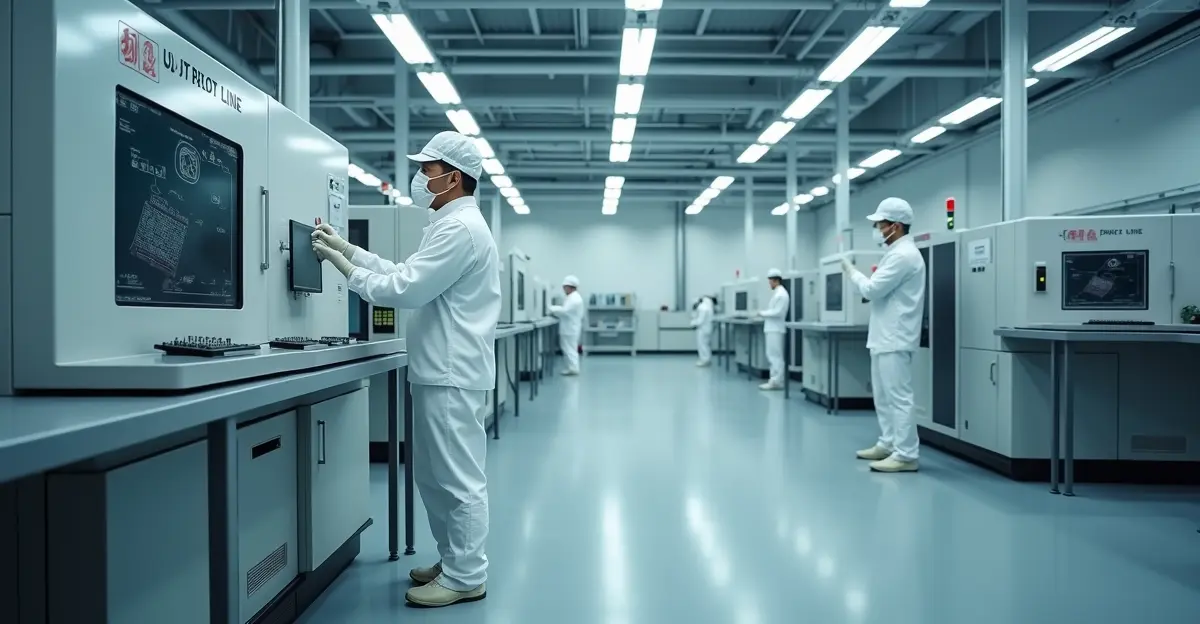
Since October 2022, the Bureau of Industry and Security (BIS) has issued seven major rule updates targeting advanced AI semiconductors and manufacturing equipment. The February 2026 expansion added semiconductor equipment and EDA software to restricted lists, extended the Foreign Direct Product Rule to more than 40 countries, and added 180+ entities to the Entity List. These controls follow the CHIPS Act investments that have begun to rebalance U.S. production: TSMC's Arizona fab now ships 4nm wafers, Samsung's Taylor site runs 3nm gate-all-around (GAA) chips, and Intel's Ohio module produces 18A-class wafers.
The result is a semiconductor supply chain split between two systems: one aligned with U.S. and allied export rules, and a parallel network serving China and other restricted markets.
Fragmentation Costs and 'Friendly Shoring'
Parallel supply chains are expensive. According to industry data, fragmentation adds 25–35% to landed costs for advanced chips in controlled markets, driven by duplicate qualification, logistics, and compliance overhead. TSMC has raised advanced-node wafer prices 3–10%, with 2nm wafers approaching $30,000, while Texas Instruments and Analog Devices implemented 10–30% price hikes.
Multi-Region Sourcing and Strategic Buffers
Procurement teams are responding with dual qualification, bill-of-materials audits, and 6–12 month strategic inventory buffers. A new 'friendly shoring' pattern concentrates leading-edge production among the U.S., Japan, South Korea, Taiwan, the Netherlands, and Germany, with India emerging as an OSAT hub and joining the U.S.-led Pax Silica alliance in February 2026.
This shift is further explained by export control compliance requirements that now touch more than 40 countries through the Foreign Direct Product Rule.
China's Domestic Chip Race
Unable to access EUV lithography, China is accelerating domestic fab construction and AI chip alternatives. Huawei targets up to 1.6 million Ascend dies in 2026, including around 600,000 Ascend 910C chips, and launched the Ascend 950PR at 1.56 petaflops FP4. ByteDance has committed $5.6 billion in orders, and DeepSeek v4 reportedly runs entirely on Huawei silicon. Cambricon aims for 500,000 accelerators in 2026.
Yet bottlenecks persist: SMIC lacks EUV access, Cambricon yields hover around 20%, and HBM plus advanced packaging remain constrained. The China semiconductor self-sufficiency push targets doubled capacity within three years via a $30 billion fund, but progress below 5nm is capped by equipment restrictions.
Impact on AI Development and Industrial Policy
The silicon divide is already influencing AI roadmaps. U.S. and allied firms benefit from onshore advanced capacity, but higher wafer costs and compliance friction slow some deployments. For restricted markets, fragmented architectures and limited tool access could delay next-generation model training by 6–12 months.
Daniel Takahashi, the author of this analysis, warns: The semiconductor map is being redrawn along geopolitical fault lines, and the cost is being borne by every AI developer — whether through higher chip prices, longer lead times, or constrained compute.
Industrial policy is now inseparable from AI infrastructure investment, as governments treat leading-edge fabs as strategic assets akin to nuclear facilities.
Frequently Asked Questions
What are AI chip export controls?
They are U.S. Bureau of Industry and Security rules restricting the sale, reexport, and transfer of advanced AI semiconductors, manufacturing equipment, and EDA software to China and other specified countries.
How much have these controls raised chip costs?
Fragmentation adds an estimated 25–35% to landed costs for advanced chips in controlled markets, with some suppliers raising prices 10–30%.
Can China replace NVIDIA chips domestically?
China is scaling Huawei Ascend and Cambricon alternatives, but EUV access limits, low yields, and HBM bottlenecks make full replacement unlikely before 2027 at the earliest.
What is 'friendly shoring'?
It is the concentration of advanced semiconductor manufacturing among allied nations — the U.S., Japan, South Korea, Taiwan, the Netherlands, and Germany — to reduce dependence on China.
How does the CHIPS Act affect U.S. capacity?
CHIPS Act funding helped raise U.S. advanced chip capacity from about 12% in 2020 to 22% in 2026, with three leading-edge fabs now in volume production.
Conclusion: A New Silicon Geography
By late 2026, the global semiconductor map will be defined by two parallel ecosystems, higher structural costs, and concentrated allied manufacturing. The race between U.S.-led controls and China's domestic buildup will determine AI development timelines and tech sovereignty for the rest of the decade.
Follow Discussion